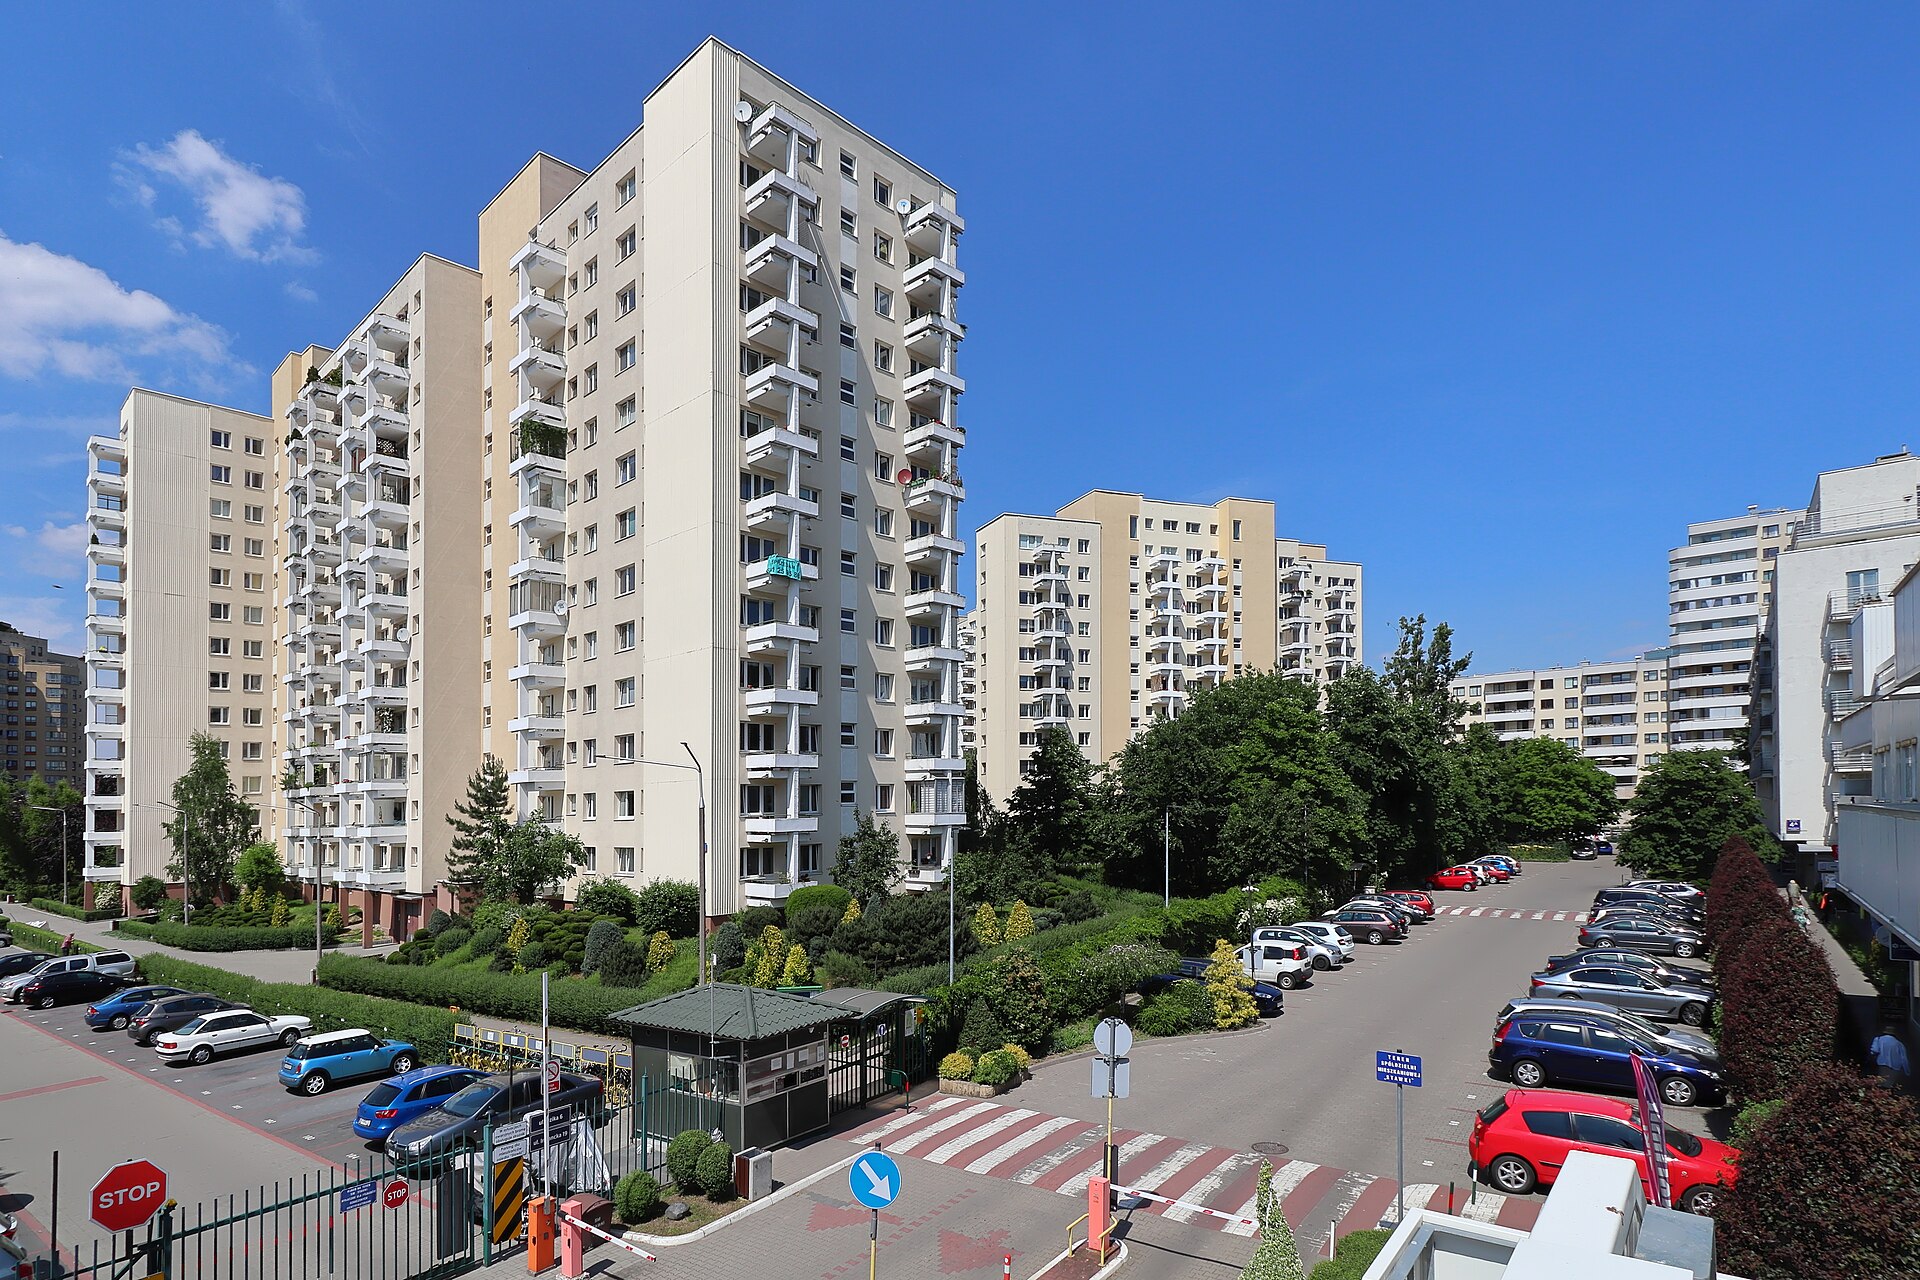
Developers in Poland’s seven largest cities sold around 13,000 new flats in the third quarter of 2026, the best result of the year, yet asking prices barely moved. Behind the headline sit more than 17,000 finished but unsold flats, a widening gap between cities, and a central bank that has stopped cutting. For investors, the Poland housing market in Q3 2026 is a demand story with a supply footnote that matters more than it looks.
Demand is back, but on the buyer’s terms
The third quarter was the strongest of 2026 on every monitor, even if the monitors disagree on the exact count. Otodom puts developer sales across Warsaw, Kraków, Wrocław, the Tricity, Poznań, Łódź and Katowice at 13,100 flats, roughly a quarter more than a year earlier, with 5,100 of them in September alone, the best month of the year. Tabelaofert counts 12,900 sales, 12.3% more than in the second quarter and almost 11% above the third quarter of 2025. JLL, which applies a narrower definition, reports 12,500 sales, up 5.7% quarter on quarter.
The pipeline behind those sales is unusually full: Otodom counts a record 3,500 new reservations in September and 7,200 open at month-end. New launches slowed to 11,000 flats in the quarter, 16% fewer than in the second quarter, so sales exceeded new supply by around 2,200 units and the available offer shrank to just under 59,000 flats on Otodom’s count, or about 70,000 on the broader JLL and Tabelaofert definitions.
Context matters, though: the first three quarters of 2025 were among the weakest of the decade, so a large part of the year-on-year gain is base effect rather than boom.
Prices: flat on the surface, diverging underneath
Stronger sales have not translated into pricing power. Tabelaofert’s average asking price across the seven markets stood at just over 16,200 PLN per square metre in September, unchanged from August and only 3% above December 2025. Year on year, JLL has Warsaw asking prices up 6.8%, Poznań 6.0% and Wrocław 5.2%, while Katowice slipped 0.4%.
The more telling figure is the distance between asking and achieved prices. In Warsaw, JLL puts the average asking price at almost 20,000 PLN per square metre and the average sold price at about 18,400 PLN, a gap of roughly 8%. In the Tricity the gap is 2,200 PLN per square metre. JLL attributes most of it to mix, because the offer is heavy with expensive apartments while sales concentrate on mainstream flats, but it also means headline averages overstate what buyers actually pay.
The secondary market tells the same story with harder numbers. The Metrohouse and Credipass barometer, based on notarial deeds, shows Warsaw transaction prices rising 6.3% quarter on quarter to 16,823 PLN per square metre, Kraków flat at 14,090 PLN, Gdańsk at 13,499 PLN and Wrocław at 12,086 PLN. Łódź fell 5.0% in the quarter to 7,342 PLN, the only large city with an annual decline. Selling times in Warsaw have lengthened to 129 days, and only just over a fifth of flats changed hands at the asking price. “The market has not died, it has simply stopped running on emotion,” is how Credipass expert Andrzej Łukaszewski puts it.
The 17,000 finished flats problem
The quarter’s most important number is not a sales figure. According to JLL, more than 17,000 completed flats were unsold at the end of September, nearly double the level of a year earlier. Ready units now make up 25% of the total offer, against 16% in September 2025. The concentration is regional: finished flats account for 38% of the offer in Katowice, 33% in Łódź, 31% in Poznań and 29% in Kraków, but only around 20% in Warsaw and Wrocław and just over 10% in the Tricity. At the current sales pace, JLL estimates that Łódź would need more than two years and Katowice almost three to clear its stock, whereas Warsaw’s offer matches demand.
Finished stock is a cost for developers and a negotiating lever for buyers: Tabelaofert reports that ready-to-move-in flats made up 34% of third-quarter transactions, and Otodom’s Katarzyna Kuniewicz expects promotions to reappear in November and to be “certain” in December, repeating the pattern of 2025.
The supply pipeline points the same way. GUS data for January to August 2026 show 153,500 dwellings started nationwide, up 4.8% year on year, and 193,300 permits, up 14.9%, with developer permits rising 20.6% to 127,400. Permits run well ahead of starts, which suggests developers are building option value rather than breaking ground, but the overhang will land in 2027 and 2028. For comparison, Destatis counts 148,800 approved dwellings in Germany for January to July, up 12.9%, while German residential prices rose just 0.6% year on year in the second quarter.
The NBP is on hold, and that is the risk
On 7 October the Monetary Policy Council left the reference rate at 3.75%, where it has stood since the only cut of the year in March. The reason is inflation: the GUS flash estimate for September came in at 4.0% year on year, above the upper bound of the NBP’s 2.5% target band for the first time in 14 months, driven mainly by fuel. Governor Adam Glapiński said he does not foresee a hike in November but did not rule one out, and that he sees “full determination” on the Council not to miss the moment if second-round effects appear.
Markets are less patient than the Council. FRA contracts cited by Bossa imply a reference rate of around 4.2% by year-end, ING reads market pricing at roughly 100 basis points of tightening and considers it too aggressive, expecting pre-emptive hikes of 25 to 50 basis points in early 2027 instead. JLL’s base case is that rates will not fall before mid-2027 and that borrowing costs will rise in the coming quarters. With CPI at 4.0% and the policy rate at 3.75%, the ex-post real rate is already negative.
Mortgage demand is still growing but losing momentum. BIK’s September index rose 17.2% year on year, the number of applicants was 9.7% higher than a year earlier but down just over 10% on August, and the average requested loan reached 522,400 PLN, up 6.9% year on year. JLL adds that 25 to 30% of new lending in the third quarter was likely refinancing rather than purchase, which flatters the headline.
What this means for investors
- Underwrite on transaction prices, not asking prices. With gaps of 8% in Warsaw and more in the Tricity, business plans built on portal averages will miss. Use notarial data and project-level sales reports.
- Treat finished stock as an entry point. In Katowice, Łódź, Poznań and Kraków, completed units are 29 to 38% of the offer and developers carry the cost. Portfolio purchases of ready flats, including for institutional rental, should price in that leverage.
- Warsaw and the Tricity are balanced, the rest are not. JLL sees Warsaw’s offer matching demand and the Tricity with the lowest share of ready stock. Land and forward-funding strategies should follow that absorption map rather than national averages.
- Model rates at 4.25% or higher, not 3.75%. Markets price hikes, JLL sees no cuts before mid-2027, and the real policy rate is negative. Development exits in 2027 and 2028 will meet buyers with less, not more, mortgage capacity.
- Margins, not prices, are where the squeeze will show. JLL flags rising energy, material and regulatory costs against limited room to raise prices. Developers with cheap land and low leverage keep their margins; the others will discount, as Otodom expects from November.
Prime East is a real estate investment and development boutique with a presence in Hanover, Berlin and Warsaw. We acquire and develop residential and commercial assets, accompany transactions on the buy and sell side, and give investors access to opportunities in both Germany and Poland. We have written before about how residential development returns compare between Poland and Germany and about what the ECB’s rate turn means for German property yields; this quarter’s Polish data complete that picture.
Conclusion
Poland’s housing market has found a floor, not a ceiling. Demand returned in the third quarter of 2026, but it returned to a market with 17,000 finished flats, lengthening selling times and a central bank that has stopped easing. Buyers have the stronger hand and are using it, which is why record sales and flat prices coexist. For investors that is a healthier set-up than a price spiral: entry prices are negotiable, absorption is measurable city by city, and the main risk, interest rates, is visible rather than hidden. The discipline required is to price the next two years at higher rates and lower prices than today’s averages suggest.
Talk to us
Are you holding finished stock in Poland, evaluating a residential land purchase, or looking for a German or Polish partner for your next development? Prime East analyses absorption, financing scenarios and exit routes for individual assets and portfolios in Warsaw, Berlin and Hanover. Contact us for a confidential conversation.
Disclaimer: This article is for general information only and does not constitute investment, legal or tax advice. All figures are based on publicly available sources.
Sources
- Otodom: 13.1 thousand developer flats sold in Q3, year-end could be up to 20% better (8 October 2026)
- Rzeczpospolita: Housing market, calm moves by sellers, no bold purchase offers (6 October 2026)
- Rzeczpospolita: Warsaw and Poznań break sales records, the client still holds strong cards (12 October 2026)
- IleZaMetr / JLL: Q3 2026, ready flats at 25% of the offer, rate concerns (14 October 2026)
- IleZaMetr / Metrohouse and Credipass: Transaction prices Q3 2026 (9 October 2026)
- IleZaMetr: Flat sales Q3 2026, developer targets (4 October 2026)
- IleZaMetr / GUS: Housing construction January to August 2026 (23 September 2026)
- Strefa Inwestorów: Monetary Policy Council decision, October 2026 (7 October 2026)
- Stowarzyszenie Inwestorów Indywidualnych: Rates unchanged in October, market pricing and analyst views (7 October 2026)
- Parkiet: Glapiński on interest rates, press conference of 8 October 2026
- Strefa Inwestorów / BIK: Mortgage demand index, September 2026 (12 October 2026)
- Destatis: Residential property prices Q2 2026 (24 September 2026)
- Destatis: Building permits for dwellings, July 2026 (18 September 2026)